For generations, accounting firms have sold one thing above all else: time. Accountants record chargeable hours, utilisation drives performance, billings drive revenue, and partner economics are built around leverage.
AI breaks that equation. If an accountant can analyse financial data, research tax issues or prepare working papers in minutes rather than hours, what should the client pay? And who receives the productivity dividend — the accounting firm, the client or the employee?
Under time-based billing, there is an uncomfortable paradox. The more efficient the accountant becomes, the fewer hours there are to bill.
For decades that didn’t matter much. Spreadsheets, accounting software and offshore processing improved productivity incrementally. AI is different. It can collapse hours of professional labour into minutes.
This isn’t merely a pricing problem for KPMG, PwC, Deloitte and EY. Accounting firms have built entire organisational systems around time — utilisation targets, staffing, promotion, remuneration and partnership economics. Remove time as the organising principle and you potentially change the firm itself.
Fixed fees are one alternative. Subscriptions are another. Value-based pricing asks a more fundamental question: what was the advice actually worth?
A tax strategy that saves a client $2 million isn’t worth less because AI helped an accountant develop it in two hours rather than twenty. Indeed, greater efficiency should arguably increase the value proposition rather than diminish it.
AI isn’t eliminating accounting expertise. It is exposing something we’ve known all along. Clients don’t buy hours. They buy expertise, judgement and outcomes.
Perhaps the biggest disruption AI poses to the Big Four isn’t replacing accountants. It’s destroying the economic logic of the billable hour.
For generations, law firms have sold one thing above all else: time. Lawyers record their work in six-minute units. Billable-hour targets influence performance, promotion and remuneration. Partner economics depend heavily upon leverage — lots of lawyers recording lots of hours.
AI breaks that equation. If legal research that once took eight hours can be completed in thirty minutes, what should the client pay? And who receives the productivity dividend — the law firm, the client or the lawyer?
Time-based billing creates an increasingly obvious paradox. The more efficiently a lawyer solves the client’s problem, the fewer hours there are to bill.
Technology has been challenging this model for years. Digital research replaced libraries, document automation accelerated drafting and outsourcing reduced the cost of routine legal work. Generative AI is different. It can potentially compress hours of research, review and drafting into minutes.
This isn’t merely a question of hourly rates. Law firms have built entire organisational systems around billable time — graduate recruitment, leverage, utilisation, promotion, partner remuneration and profitability. Remove time as the organising principle and you potentially change the economics and structure of the law firm itself.
Fixed fees are one alternative. Retainers are another. Value pricing asks a different question: what was the legal outcome actually worth?
Advice that prevents a $20 million commercial mistake isn’t worth less because an experienced lawyer, assisted by AI, produced it quickly. The time taken to reach the answer was always an imperfect proxy for the value of getting the answer right.
Clients never really wanted hours. They wanted judgement, expertise and outcomes.
AI may not kill the lawyer. It may kill the billable hour.
Executive education has traditionally started with the curriculum. Harvard, INSEAD, Wharton and other leading business schools decide what executives need to learn, assemble the faculty, design the program and invite participants to enrol.
What if we reversed it?
Start with the executive. What do they already know? What don’t they know? What are they curious about? What problems are they trying to solve? Where do they want their career to go? Then design the curriculum around them.
Until recently, that would have been difficult and expensive. AI changes the economics of customisation. It makes it possible to imagine an executive education program with a cohort of one.
A CFO might combine artificial intelligence, strategy, geopolitical risk and leadership. A professional services partner might choose business development, psychology, negotiation and organisational design. An entrepreneur might want finance, marketing, governance and technology. There is no particular reason these people should follow the same curriculum.
There is also no reason every subject should be taught in the same way. A participant might learn finance from a professor, strategy from a practitioner, leadership through coaching and negotiation through simulation. AI can explain concepts, generate exercises, challenge assumptions, curate material and adapt the learning as the executive develops.
The role of the business school changes accordingly. Instead of asking executives to choose from a catalogue of programs, Harvard, INSEAD or Wharton could help them answer a much more interesting question: what should I learn next?
The curriculum could then evolve. An acquisition creates a need to understand valuation. A promotion introduces new leadership challenges. Expansion into Asia creates an interest in geopolitics and culture. A board appointment creates a need for governance. Development follows the executive rather than the executive following the program.
That also changes the unit of executive education. Instead of buying a three-day course or a twelve-week program, an executive could build a learning relationship that lasts for years.
AI doesn’t diminish the value of great teachers, business schools or executive education. It makes personalisation possible at a level that previously wasn’t practical.
Perhaps the next innovation in executive education isn’t another course.
For most people, carrying $1.2 billion in debt would be a terrifying prospect. But for Rich Dad, Poor Dad author Robert Kiyosaki, it’s no cause for concern. And an August 2026 Vanity Fair profile offers some important context behind that eye-popping figure.
Kiyosaki doesn’t personally owe $1.2 billion, according to his former wife and longtime business partner Kim Kiyosaki. Rather, the debt is held by a group of real estate investors, including Kiyosaki and his partners, tied to roughly 1,500 apartment units. His personal share is reportedly much smaller (1).
Must Read
Jeff Bezos backs a platform that lets anyone invest in rental homes for as little as $100 — 6 ways to build wealth like a landlord without actually being one
JPMorgan sees gold hitting $5,000/oz by Q4 — and savvy investors are protecting their wealth with a tax-advantaged Gold IRA. Get your free guide from Priority Gold
The tax breaks in Trump’s ‘big beautiful bill’ expire after 2028. Here are 4 moves to make before the window closes
In a prior appearance on The Iced Coffee Hour podcast, the hosts asked Kiyosaki a blunt question: “How much debt do you have?” Kiyosaki didn’t hesitate. “$1.2 billion,” he replied (2).
The figure may be eye-popping, but it fits neatly with Kiyosaki’s long-running philosophy: Use borrowed money to acquire assets that can generate income and appreciate over time.
When asked on the podcast whether that amount made him nervous — or worried about defaulting — Kiyosaki laughed.
“Are you sh-tting me?” he said. “No. I’ll tell you why. If you owe the bank $20 million and you can’t pay it back, you got a problem. But you owe the bank $1 billion and you can’t pay it back, it’s their problem.”
That quip, a modern echo of J. Paul Getty’s famous line, reflects Kiyosaki’s philosophy on money: Use debt strategically, not fearfully. When asked why the bank gave him such an astronomical loan, he needed only two words — “real estate.”
Indeed, investing in property often requires leverage, whether you’re buying your first rental unit or scaling a portfolio. For Kiyosaki, that mindset goes back decades — and runs counter to conventional wisdom.
“Debt is money. My poor dad always says, ‘Get out of debt,’ Dave Ramsey says, ‘Get out of debt.’ My rich dad says, ‘Only lazy people use their own money — your job is to borrow money,'” Kiyosaki explained in a recent interview with Hannah Hammond (3).
And he’s clearly followed that advice. “We’re always buying real estate because we use debt — and we pay no tax legally,” he said.
‘I make a lot of money’
Kiyosaki’s point comes down to how real estate investors can legally reduce their tax burden by using debt strategically. When investors purchase properties with borrowed funds, the interest payments on those loans are often tax-deductible — even when the properties themselves generate positive cash flow.
The strategy Kiyosaki describes is pretty simple: Borrow against an asset rather than sell it. If a property gains value, an investor may be able to tap that equity for cash without triggering the capital-gains tax that could come with selling the property.
Of course, that doesn’t mean the money is free. The debt still has to be repaid and the strategy only works if the underlying investment can generate enough income to keep up with the loan.
“I own hotels today and 15,000 rental properties — and make a lot of money and pay no tax. I love it,” he revealed.
Real estate can indeed be a powerful tool for preserving — and building — wealth. It’s no wonder that real estate accounts for nearly 25% of the typical family office portfolio.
It can generate steady rental income, serve as a hedge against inflation and provide valuable tax perks that help investors keep more of what they earn while growing their portfolios.
Still, while Kiyosaki has thrived using substantial debt to expand his empire, that strategy may not be for everyone. Leveraging a large amount of borrowed money amplifies both gains and losses — and without reliable cash flow or experience managing properties, even a small downturn in the market or a rise in interest rates can quickly turn manageable debt into a financial burden.
And the time, effort and costs involved in managing and maintaining multiple properties prevent many from investing. So unless you’re a hedge fund titan or an oil baron, you’ve been shut out of one of the most profitable corners of the market.
The good news? You don’t need to be as wealthy as Kiyosaki — or take on massive debt — to start investing in real estate. For investors who like the idea of real estate income but don’t want to deal with the headaches of owning and managing a property themselves, there are other ways to get in.
Mogul bridges the divide here. This real estate investment platform offers fractional ownership in blue-chip rental properties, which gives investors monthly rental income, real-time appreciation and tax benefits — without the need for a hefty down payment or 3 a.m. tenant calls.
Founded by former Goldman Sachs real estate investors, the mogul team handpicks the top 1% of single-family rental homes nationwide for you. Simply put, you can invest in institutional-quality offerings for a fraction of the usual cost.
Each property undergoes a vetting process, requiring a minimum 12% return even in downside scenarios. Across the board, the platform features an average annual IRR of 18.8%. Their cash-on-cash yields, meanwhile, average between 10% and 12% annually. Offerings often sell out in under three hours, with investments typically ranging between $15,000 and $40,000 per property.
Every investment is secured by real assets, not dependent on the platform’s viability. Each property is held in a standalone Propco LLC, so investors own the property — not the platform. Blockchain-based fractionalization adds a layer of safety, ensuring a permanent, verifiable record of each stake.
For decades, advertising agencies have had a relatively simple way of costing their work. Estimate the people required, estimate their time, add overhead and margin, and arrive at an agency fee. Even where clients pay a retainer or fixed project fee, people and time often sit somewhere underneath the calculation.
AI changes the arithmetic.
A copywriter can generate and explore dozens of creative directions in the time previously required to develop a handful. An art director can visualise concepts before a production team becomes involved. Strategists can synthesise research, analyse competitors and interrogate customer data dramatically faster.
That sounds like an extraordinary productivity dividend for agencies such as Ogilvy, DDB, Leo Burnett and Saatchi & Saatchi.
But who gets it?
If an advertising campaign that previously required 500 agency hours can be developed in 250, should the client pay less? Does the agency retain the difference as margin? Do creatives work fewer hours? Or does the agency simply produce twice as much work?
There is an even more uncomfortable question. What happens when clients acquire many of the same AI capabilities themselves?
The problem is particularly acute in advertising because time was never a particularly good measure of creative value in the first place. A copywriter who arrives at the winning line in twenty minutes hasn’t created less value than one who takes two days. An advertising idea that transforms a brand isn’t twice as valuable because twice as many people attended the brainstorm.
Yet much of the agency business model has historically required some relationship between the cost of people, the time they spend and the fee ultimately charged to the client.
AI weakens that relationship.
The obvious response is to move further towards outputs, fixed fees, retainers, licensing, performance incentives or other forms of value-based remuneration. But that creates another problem: agencies then have to become much better at answering a question that time conveniently avoided.
What is creativity worth?
AI may make advertising agencies extraordinarily more productive. But productivity isn’t necessarily the prize if your commercial model depends upon selling the inputs that AI is eliminating.
Perhaps the biggest AI challenge facing the advertising industry isn’t whether machines can become creative.
It’s whether agencies can stop charging for the time it takes humans to be creative.
That last line is where this version earns its own existence. It isn’t merely the accounting article with accountant replaced by copywriter.
And semantically it’s loaded without looking loaded: Ogilvy, DDB, Leo Burnett, Saatchi & Saatchi / advertising agencies / agency fee / copywriter / art director / strategists / campaigns / clients / creative / brand / advertising industry.
If LinkedIn can’t recognise Advertising Services from that, our hypothesis has a problem.
What happens to consulting economics when analysis that once took a team several days can be completed in hours?
For decades, management consulting has operated on a familiar model. Assemble a team, allocate consultants, analyse the problem, produce the recommendations and charge the client according to the people, expertise and time required.
AI changes the arithmetic. Research can be accelerated, data analysed faster, interviews synthesised almost instantly and presentations drafted in minutes. Work that once required five consultants may eventually require three. Work that took three weeks may take one.
That’s an extraordinary productivity dividend. But who gets it — McKinsey, the client or the consultants?
If BCG can deliver the same quality engagement with substantially fewer professional hours, should its margins rise? Should the client pay less? Should consultants work fewer hours? Or should the firm simply undertake more work?
This is bigger than pricing. The traditional consulting model is built partly upon leverage, with partners and senior leaders supported by progressively larger groups of consultants doing analysis and execution. AI potentially changes the shape of that pyramid.
And that raises an even more fundamental question. If clients themselves have access to increasingly capable AI, what exactly are they buying from Bain, BCG or McKinsey?
Probably what they were buying all along: judgement, pattern recognition, experience, independence, facilitation and confidence in difficult decisions.
AI doesn’t necessarily diminish those things. It may make them more visible.
The future of consulting therefore isn’t simply about consultants learning to use AI. It’s about deciding what a consulting firm is selling when it is no longer selling professional labour.
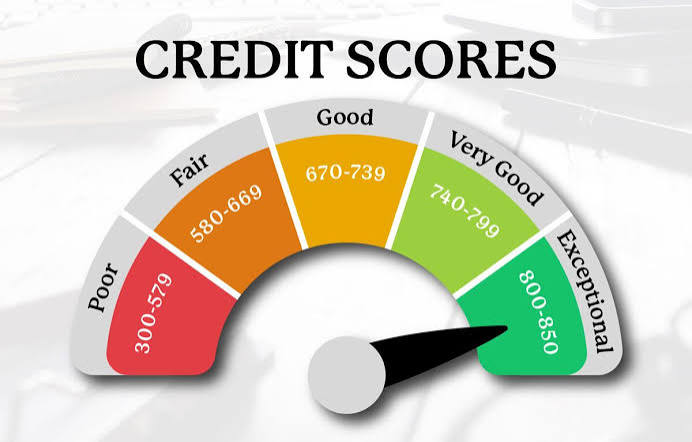
I had a default on my credit file for six months. It was an error. It caused my credit score to plummet. There was just one problem: I didn’t know it was there.
Banks tell you to get a copy of your credit file. They don’t tell you there is/ was three credit bureaus.
I was monitoring my credit – with ONE bureau. I assumed it was the only one that really mattered. It wasn’t. In fact the banks tell you categorically, “It doesn’t matter which bureau you obtain your credit report from – they’re all the same.”
I am here to tell you that is outright incorrect.
I could see my credit score and nothing I was looking at alerted me to the problem. The default had been recorded with the ONE credit bureau I wasn’t following. The ONE credit bureau my bank reported to.
That experience taught me something remarkably basic about credit reporting.
You DON’T have one credit file.
For my purposes, there were three credit reporting bodies that mattered: Equifax, Experian and illion. Experian and Illion merged last year. They don’t necessarily hold identical information about you. Consequently, the picture presented to a lender can differ depending upon which credit reporting body it uses.
Until this happened to me, I hadn’t given much thought to that distinction. I suspect I’m not alone.
Even the language encourages the assumption. What’s your credit score? Check your credit score. Improve your credit score. We talk about it in the singular, as though there is one definitive number sitting somewhere that represents our creditworthiness.
I had been doing what seemed perfectly sensible. I was monitoring my credit information. But I wasn’t monitoring all of it. An adverse entry could therefore sit on one file while being absent from another.
That raises a more interesting question. What exactly does a credit score represent?
We tend to treat numbers as absolutes. A score of X appears better than a score of Y. The precision of the number gives it an air of objectivity. But the number is produced from information, and different information can produce a different representation.
My underlying financial circumstances hadn’t suddenly changed because an erroneous default appeared on one credit file. The information about me had changed. That’s an important distinction.
There was something fascinating about discovering that three organisations could maintain different representations of the same person. I hadn’t become three different borrowers. Yet there could effectively be three different pictures of my credit history.
That matters because lenders don’t make decisions about some perfectly known version of us. They make decisions using information. That information can differ between systems. It can be incomplete. And, as I discovered, it can be wrong.
For six months an error existed in a financial information system that mattered to me. I didn’t know about it because the credit bureau I happened to be watching wasn’t the bureau where the problem existed.
We tend to associate financial literacy with budgeting, investing, superannuation, mortgages, compound interest and perhaps understanding financial statements. All of those things are useful. But perhaps financial literacy starts somewhere more elementary.
It starts with understanding the systems through which our financial lives are represented. What information exists about me? Who holds it? How is it used? What assumptions am I making? And what don’t I know because I’ve never thought to ask?
That’s less about financial advice than conscious inquiry.
My experience with the default didn’t initially teach me how to invest money or manage a balance sheet. It did something more fundamental. It exposed an assumption I didn’t know I was making.
It’s one of those expressions that sounds so obviously true that we rarely stop to examine what it actually says. Show me the evidence. Show me the numbers. Show me that it works. Show me someone who has done it before. Once I can see it, measure it, touch it or demonstrate it, I’ll believe it.
But there is a problem.
If you can only believe what you can already see, you can only see what already exists.
Everything genuinely new begins somewhere else.
Before the first aeroplane flew, there was no flying aeroplane to point to. Before a business exists, there are no customers, revenues or financial statements proving that it works. Before an invention becomes an invention, there is no physical object to examine. Before a different future becomes real, there is no evidence of that future.
The evidence arrives later.
We have confused the order of things.
Seeing does not necessarily produce believing. Very often, believing produces seeing.
Believing IS SEEING.
This is not an argument for positive thinking. Nor is it the familiar promise that if we believe strongly enough, the universe will deliver whatever we desire. Belief does something both simpler and more profound: it changes what becomes visible to us.
Two people can encounter precisely the same circumstances and see entirely different things. One sees an obstacle; another sees an opening. One sees a fixed constraint; another sees something that can be redesigned. One sees failure; another sees information. Nothing in the external landscape necessarily changed. What changed was the lens through which the landscape was perceived.
Belief is such a lens.
And lenses do more than help us see. They determine what enters our field of vision and what remains outside it.
This becomes particularly important when we consider potential.
We routinely speak of potential as though it were something an individual possesses. She has enormous potential.He hasn’t fulfilled his potential.We need to unlock their potential. In doing so, we turn potential into something finite — a capacity hidden somewhere inside a person waiting to be measured, developed and eventually exhausted.
But what if we have the relationship backwards?
In order for something to manifest, it must first have the potential to manifest.
Potential therefore precedes manifestation. The visible emerges from the not-yet-visible. Form emerges from that which has the potential to take form.
Suddenly “seeing is believing” looks strangely limiting. It asks manifestation to provide proof of potential when potential necessarily came first.
This limitation appears everywhere in organisations.
Show me the business case. Show me the precedent. Show me the benchmark. Show me the comparable organisation. Show me the data demonstrating that this will work.
These are entirely reasonable questions when we are evaluating something that already exists. They become much more problematic when we are trying to create something that does not.
The genuinely unprecedented cannot provide precedent.
Perhaps this explains one of the paradoxes of innovation. Organisations proclaim their desire for innovation while constructing decision-making systems designed to privilege what can already be demonstrated. We ask people to imagine the future and then require the future to produce evidence before we permit them to create it.
We demand to see before we believe.
And then wonder why we keep reproducing variations of what we already know.
Believing is not certainty. It is not prediction. It is not knowing what something will become. Perhaps belief, at its most useful, is simply our willingness to acknowledge possibility before possibility has acquired form.
That distinction matters.
The moment we decide something is impossible, an entire landscape disappears from view. We stop asking certain questions. We stop noticing particular connections. We stop experimenting. We stop looking. The potential may remain, but our relationship with it has changed.
Conversely, when we entertain the possibility that something could exist, we begin to see differently. We notice pathways that were previously irrelevant. We make connections we previously overlooked. We ask questions that would otherwise never have occurred to us.
The world did not suddenly acquire potential.
We became capable of seeing it.
Perhaps, then, the old expression deserves to be turned on its head.
Seeing asks: What IS?
Believing asks: What COULD BE?
Both have their place. We need evidence. We need discernment. We need to understand the world as it presently manifests.
But we should be careful not to mistake the limits of what we can presently see for the limits of what is possible.
Because everything we can see today was once unseen.
And before something can become visible, someone must first become capable of seeing what isn’t there yet.
A lot of people confuse masculine with male and feminine with female, and that is quite misleading. At their core masculine and feminine are energetic polarities. And if you have been exploring my writing for a while I’d also have you believe that THE feminine is a bit more than merely a polarity – it is also the source of all creation. But that’s another discussion.
On occasion I use synonyms when describing masculine and feminine energy. Perhaps the easiest to comprehend is that THE feminine is relational. It is of the source, by the source and forever remains connected to the source. So when we explore the language of THE feminine we state in unambiguous terms that this thing only exists in communion with something else, ultimately as part of an indivisible whole. Nothing is entirely separate. Its meaning emerges through relationship. Anyway, enough of the semantics. Let’s bring this into a practical conversational piece.
Time and money are inescapable realities of modern business. They are also routinely used as surrogates for each other and conflated with measurements of value. We spend time. We save time. We waste time. We invest time. We buy time. Time is money. Equally, money becomes a convenient proxy for value, contribution, importance and sometimes even human worth. Salary becomes a measure of success. Revenue becomes a measure of organisational significance. An hourly rate becomes a measure of expertise. We have become extraordinarily accustomed to quantifying things and then assuming the quantity tells us something about their value.
Our everyday business parlance has masculine and feminine language bias embedded into it. Consider something as commonplace as employment. We talk of labour hire and employment as full-time, part-time or even casual. Note that these terms are what I would call feminine in that they are relational or relative. They are not absolute measures in the way a masculine description might be. Part-time only makes sense in relation to full-time. “Full” itself only makes sense because we have collectively decided what constitutes a full working week. A masculine description might instead be hours, units or dollars: 38 hours, five days, $2,000, forty units. Measures that are discrete, defined and designed to stand alone.
That distinction is subtle but important. One way of thinking tells us how much. Another tells us in relation to what. Neither is inherently better. The interesting question is which one we habitually privilege, particularly in business.
When we talk about money we routinely describe it as more, less, enough, rich, poor, surplus, deficit, expensive or cheap. All of these relative terms I would call feminine. They exist in relation to another variable. More than what? Less than what? Rich compared with whom? Expensive relative to what? Enough for what purpose? A person earning $100,000 can simultaneously be rich, poor, adequately paid or underpaid depending entirely upon the relationship against which that number is considered.
Even enough is an intriguing word. Enough sounds like a quantity, but it isn’t really. There is no universal number called enough. Enough only exists in relation to need, expectation, desire, circumstance or purpose. What is enough today may not be enough tomorrow. What is enough for one person may be abundance for another and scarcity for someone else. Enough is not an amount. It is a relationship. Ultimately, enough is a decision.
We even formalise this relational quality in accounting and governance through the concept of materiality. An amount does not become material simply because it reaches some universally prescribed number. Material to whom? Material in relation to what? Materiality requires context. The number may be masculine in its precision; its significance is relational.”
Integers are another example. They exist as static points of measurement. 1. 2. 10. 100. We like integers because they give us certainty. They allow us to count, compare, rank and measure. But there is a whole dynamic range between these integers. Between 1 and 2 lies 1.1, 1.01, 1.001 and effectively an infinity of possible points. The apparently empty space between two integers isn’t empty at all.
And poignantly, we use symbols to describe relationships around these points. < > + − are all symbolic representations of conditions that are not simply the fixed number itself. Less than. Greater than. Adding to. Taking from. The moment we move away from the fixed point we require a language of relationship.
The fixed points are easy to measure. The relationship between them is where things start moving.
Perhaps that distinction matters more than we realise. Business has become extraordinarily accomplished at measuring the points. Revenue. Profit. Headcount. Hours. Market share. Productivity. Utilisation. Share price. Units sold. Customer numbers. We construct dashboards filled with them. We establish KPIs around them. We compare this quarter with last quarter and this year with last year.
But what about the space between them?
What happened between $1 million and $2 million?
What happened between employee number 100 and employee number 200?
What happened between a customer satisfaction score of six and a score of eight?
What happened between 8.00am and 5.00pm?
The numbers tell us that something changed. They do not necessarily tell us what happened. They tell us where we were and where we arrived. They are much less capable of describing the relationships, interactions, conversations, decisions, failures, adaptations and moments of insight through which the change actually occurred.
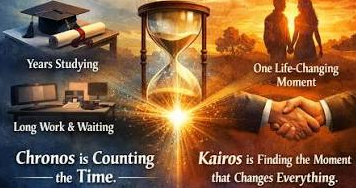
The same is true for time. There are two useful ways of thinking about its measure — Chronos, quantitative or clock time, and Kairos, qualitative time. Chronos is sequential. It can be counted. Seconds become minutes, minutes become hours, hours become days. Kairos describes something entirely different: the opportune moment, the appropriate moment, the moment at which conditions are right for something to occur.
Chronos asks: What time is it?
Kairos asks: Is it time?
One answer might be 10.37am.
The other might simply be: Ready.
That distinction is profound because “ready” has no fixed unit of measurement. You cannot necessarily determine readiness by looking at a clock. A person may be ready before the deadline or unready after it. An idea may mature in an afternoon or take ten years. A market may be technically available but not ready. A conversation can occur at the scheduled time and still happen at entirely the wrong moment.
Modern business overwhelmingly privileges Chronos. Deadlines. Timesheets. Billable hours. Quarterly reporting periods. Meeting durations. Project schedules. Financial years. Tenure. Years of experience. We measure time relentlessly because time appears objective and therefore manageable.
Then something even more interesting happens. We attach moral meaning to those measurements.
Busy becomes important.
Fast becomes competent.
Early becomes diligent.
Late becomes irresponsible.
Idle becomes lazy.
We have taken a unit of measurement and quietly turned it into a measure of human value.
A coach might tell us they have completed 1,000 hours of coaching. A consultant might tell us they have twenty years of experience. An executive might tell us they work seventy hours a week. Each statement is quantitative. But none necessarily tells us anything about quality. One thousand hours could represent extraordinary mastery or the same hour repeated one thousand times. Twenty years of experience might represent twenty years of learning or one year of learning repeated twenty times.
Time is an input. It is not necessarily an output.
There is another conception of time that our everyday language already understands perfectly well. We talk about the time it takes. The right time. When the conditions are right. When someone is ready. When an idea has matured. When something has run its course. When the time comes. In good time. In the fullness of time.
These expressions are inherently relational. Their meaning cannot be separated from context. They describe not the quantity of time that has passed but the relationship between time, circumstance and readiness.
Perhaps what fascinates me most, then, is not the points themselves but the space between them. Between beginning and ending. Between knowing and not knowing. Between one identity and another. Between the old and the new. Between death and rebirth.
This time gap between events can be depicted beautifully by the slowly moving hands of a clock. Powderfinger captured something of this in These Days:
It’s coming ’round again The slowly creeping hand Of time and its command It settles in its place Its shadow in my face Puts pressure in my day Soon enough it comes Here it is again The slowly creeping hand Of time and its command Soon enough it comes And settles in its place Its shadow in my face
The song continues that image of time settling into place and casting its shadow across the day. I find the metaphor particularly interesting because the hand itself isn’t exerting pressure. The clock doesn’t care. We do. We have taken the movement of a hand around a dial and constructed an entire architecture of expectation around it. The slowly creeping hand measures Chronos. The pressure we experience arises from our relationship with it.
Curiously, this gap between moments, and particularly between death and rebirth, is explored in Tibetan Buddhism. It is called the bardo, an intermediate or transitional state. The Tibetan term is commonly associated in the West with the period between death and rebirth, but the broader idea is that existence contains transitional states in which one condition has ended and another has not yet fully emerged.
Traditional accounts of the post-death journey describe a progression through distinct bardos. There is the Bardo of the Moment of Death, in which the physical and mental faculties dissolve and consciousness encounters what is described as the Clear Light. There is the Bardo of Reality, associated with experiences and appearances arising after death. And there is the Bardo of Becoming, the transitional movement toward another existence and rebirth. The traditional framework can describe this post-death transition as lasting up to 49 days.
Whether one approaches that literally, spiritually, philosophically or simply as metaphor, I find the underlying concept fascinating: there is a state between states.
Western business thinking is remarkably uncomfortable with that proposition.
We like beginnings and endings. Targets and outcomes. Before and after. Problem and solution. Current state and future state. Strategy and execution. Hire date and termination date. Start date and completion date. We put milestones on project plans precisely because milestones allow us to turn movement into points.
We like the measurable points.
But transformation does not necessarily occur at either end.
It occurs between them.
There is a period in which the old thing has ceased to be, but the new thing has not yet fully become. Anyone who has undergone significant personal or organisational change understands this intuitively. The old identity no longer fits, yet the new identity isn’t established. The old strategy has been abandoned, yet the new strategy isn’t working. The previous career has ended, yet the next one hasn’t begun. The old way of thinking has been questioned, yet the new understanding has not crystallised.
We often treat this space as a problem.
We call it uncertainty.
Ambiguity.
Delay.
Downtime.
Transition.
A gap.
We rush to close it.
But perhaps the gap is where the transformation is actually taking place.
Perhaps it cannot always be hurried, measured or managed.
This brings us back to time and money. Money can be counted. Time can be counted. People can be counted. Outputs can be counted. These are the fixed points we have become extraordinarily good at measuring.
But value is relational.
Enough is relational.
Readiness is relational.
Opportunity is relational.
Transformation is relational.
And relationship itself cannot be understood entirely by measuring its component parts.
Much of my work is predicated on THE RISE OF THE FEMININE, but there is a whole unconscious language bias we either use or refrain from using that points to its everyday application. What I discuss here are but a few examples.
The interesting possibility is that THE feminine is not something we need to introduce into business. It is already there. It is embedded in our language. It appears whenever we move from absolute to relative, from quantity to quality, from the isolated thing to the relationship between things.
It is hidden between our measurements.
Perhaps we have simply trained ourselves not to see it because we have become so preoccupied with what can be counted.
We count the hours. We count the dollars. We count the people. We count the outputs. We count the years. We count the points.
And all the while, something is happening in between.
We count the points.
THE feminine may be found in the space between them.
Ask the average spiritual seeker to name the symbols of masculine and feminine and they will probably reach for familiar imagery: the chalice and the blade or the phallus and the orb.
Even our most familiar symbols carry the same inheritance. The male symbol (♂) – a circle with an arrow pointing diagonally upwards – derives from the ancient astronomical symbol for Mars and has traditionally been associated with the shield and spear of the Roman god of war. The female symbol (♀) – a circle with a cross beneath it – derives from the astronomical symbol for Venus and has traditionally been associated with the hand mirror of the Roman goddess of love. Mars and Venus. Spear and mirror. Blade and chalice. Phallus and orb. Different symbols, same underlying assumption.
They are all gender-based.
They describe male and female anatomy, mythology and gender roles more readily than they describe masculine and feminine as energetic principles. We begin with gender and then infer the energy.
I’d like to offer an alternative hypothesis — one that is entirely independent of gender.
Perhaps it is best characterised in numerical terms: THE feminine is infinity. Masculine is One.
THE feminine is not a womb, a chalice, an orb or any other representation of the female form. THE feminine is infinity – unlimited potential, without boundary and before definition. Before something becomes something, every possibility remains available. THE feminine is the source of all creation.
Masculine begins when something becomes One. Its defining characteristic is not the phallus, the blade or the spear. It is individuation.
One thing. One thought. One word. One decision. One form. The moment something becomes this rather than that, distinction has occurred. Something has emerged from unlimited possibility and acquired definition. It can be identified, named and counted. It can be distinguished from everything it is not.
That is masculine.
But there is an important distinction between individuation and separation. For something to become distinct does not require it to become disconnected from that from which it arose. A wave can be identified as a wave without ever ceasing to be ocean. A branch can be distinguished from the tree without becoming independent of the tree. One can emerge from infinity without somehow finding itself outside infinity. Indeed, where would outside infinity be?
And this is where individuation can give rise to the Illusion of Separation. The illusion is not that you are an individual. Clearly, you are. The illusion occurs when individuality is mistaken for independence; when distinction is interpreted as disconnection; when I am One quietly becomes I am separate.
A masculine act of individuation is therefore not itself the problem. It is necessary for manifestation. Without distinction there is no thing, no thought, no word, no identity, no decision, no creation in form. The problem begins when One forgets where it came from, because the emergence of One creates something else at precisely the same moment.
Not-One.
The instant I identify this, I have also created that. The instant there is here, there is there. Self creates other. Inside creates outside. Subject creates object. The act of individuation doesn’t merely produce One; it creates the possibility of two.
One gives birth to polarity.
Polarity is not inherently problematic either. It is one of the consequences of manifestation. Hot and cold, light and dark, expansion and contraction, self and other: distinction allows us to experience a world of difference. But polarity remains contained within infinity. The existence of two distinguishable poles does not mean that either has somehow escaped the whole from which it arose.
The problem arises when we forget that.
When One forgets its relationship to THE feminine, polarity can become polarity consciousness: a way of experiencing reality in which the poles are no longer understood as differentiated expressions of an indivisible whole, but as separate and independent things. This becomes versus that. Me becomes versus you. Us becomes versus them. Mine becomes versus yours. Difference becomes separation.
And once separation becomes our organising assumption, an entirely different logic becomes possible. If I experience myself as separate from you, I can compare myself with you. If this is separate from that, I can measure one against the other. Once there are two, I can decide that one is bigger, faster, stronger, richer, better or more valuable than the other.
Comparison makes ranking possible. Ranking makes hierarchy possible. Separation makes ownership possible. If my interests are understood as separate from yours, I can maximise mine without necessarily accounting for yours. And if resources are understood as things existing independently of the whole, I can possess them, accumulate them and eventually seek to maximise my share of them.
None of this makes individuation or polarity inherently problematic. Quite the opposite. They make manifestation possible. Nor do comparison, measurement or even competition become inherently wrong merely because they sit downstream. The problem is more subtle than that. It is the consciousness from which we employ them.
The illusion begins when we mistake distinction for separation and then mistake separation for reality.
One has not actually left infinity. It has merely forgotten that it remains within it.
Perhaps this helps explain something much larger about the world we have created. We count things as though their numerical independence makes them relationally independent. We divide organisations into functions, economies into sectors, land into property, time into units, performance into measures and people into categories. The act of division can be enormously useful. It allows us to comprehend, organise and act. But the map can eventually obscure the territory.
What we separate conceptually can remain profoundly connected relationally.
A business can maximise profit and discover that employees, customers, communities and ecosystems were never actually external to the system upon which that profit depended. An individual can maximise income and discover that time, health, relationships and meaning were never separate variables. A society can pursue economic growth and eventually discover that the environment was never an externality.
The masculine capacity to distinguish is extraordinarily powerful. Indeed, without it very little of what we call civilisation could exist. We could not name, number, categorise, measure, analyse, organise or create form from possibility. The illusion is not distinction. The illusion is believing that what has been distinguished has therefore been disconnected.
And this introduces an important asymmetry between THE feminine and masculine. They are not two equivalent forces standing opposite one another. They are not two halves which, when reunited, somehow recreate a whole.
THE feminine is whole. It is the origin.
Infinity does not require One to complete it. One is already contained within infinity. Masculine, however, cannot exist independently of THE feminine because One must arise from somewhere. Individuation presupposes a field from which something can become individuated. Definition presupposes the undefined. Form presupposes potential.
And crucially, emergence from THE feminine does not mean departure from THE feminine. One remains within infinity.
THE feminine is the source; masculine is manifestation. THE feminine is possibility; masculine is definition. THE feminine is infinite; masculine is One. These are not competing forces seeking equilibrium. One is the field of unlimited potential; the other is what happens when possibility assumes form.
The journey is not about destroying individuality or somehow dissolving ourselves back into an undifferentiated whole. Nor is it about suppressing masculine in favour of THE feminine. It is about remembering the relationship: recognising oneself as One while remaining conscious of the infinity from which One arises; distinguishing without disconnecting; defining without forgetting relationship; individuating without succumbing to the Illusion of Separation.
And this is where our familiar symbolism has led us astray. By using male and female bodies to represent masculine and feminine, we have quietly converted a proposition about existence into a proposition about gender.
Masculine was never really the blade. Its defining characteristic was simply the moment infinity became One.
And our greater challenge began when One mistook itself for alone.